Jun 29, 2026, 5:34 PM
by
Nathan Reeves
5 min read
Digital Dollarization: What Stablecoins Mean for Emerging-Market Central Banks
Jun 29, 2026, 5:34 PM · by Nathan Reeves
For households in high-inflation economies, a dollar token is a lifeline. For their central banks, it is a leak in the monetary system that is hard to plug.
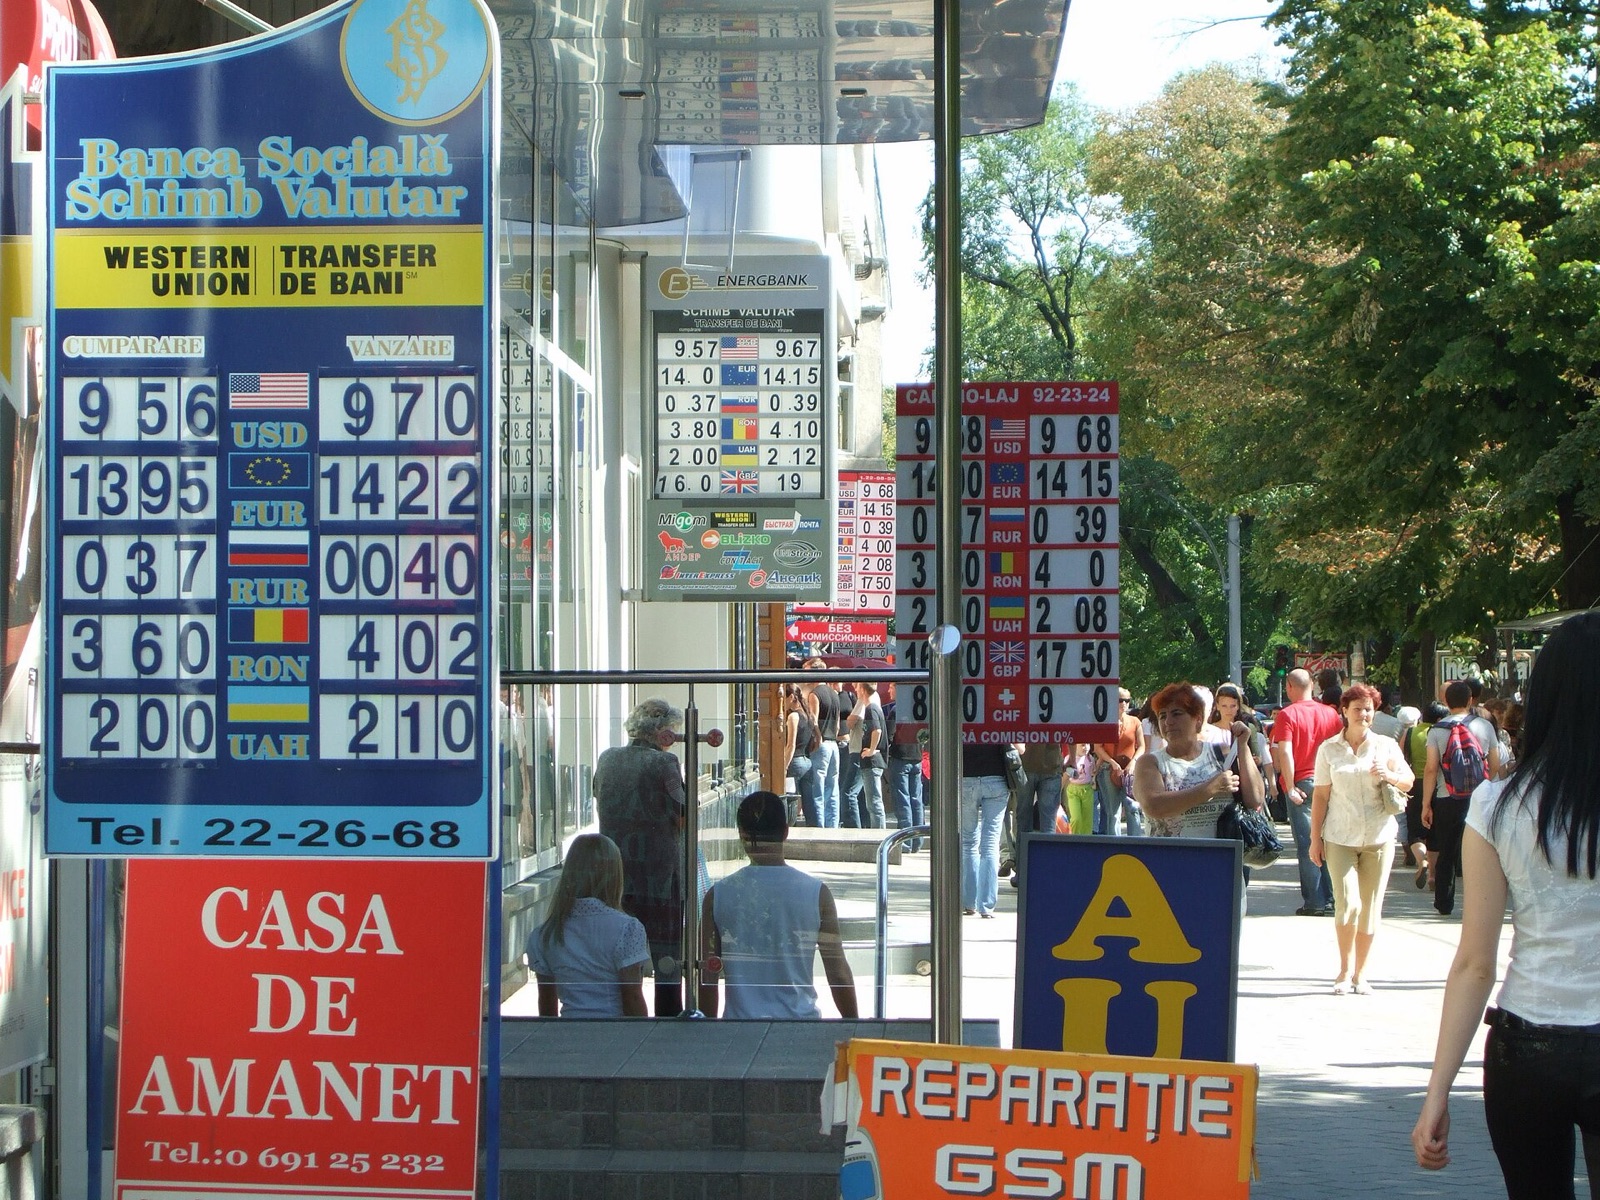
In Buenos Aires, Istanbul and Lagos, the dollar has long lived under mattresses and in informal exchange booths. What has changed over the past few years is where it lives digitally. A growing share of people in economies with volatile currencies now hold dollar-pegged tokens on their phones, move them through messaging apps and use them to pay freelancers abroad. For those households, stablecoins solve a real problem. For the central banks responsible for those economies, they pose one of the more awkward policy dilemmas of the decade.
Why demand is strongest where money is weakest
The pattern is consistent across countries. Where inflation is high, capital controls are tight or the banking system is distrusted, stablecoin use rises. Blockchain analytics firms have repeatedly placed countries such as Argentina, Turkey, Nigeria and Venezuela among the heaviest users of stablecoins relative to the size of their economies. The motives are prosaic: protecting savings, receiving remittances, paying for imports, or getting paid by foreign clients without losing a large cut to official exchange rates.
Unlike cash dollars, a stablecoin does not require a trip to a bank or an informal dealer. It can be bought peer to peer, held in a self-custody wallet and sent across borders in minutes. That makes it the most accessible form of dollarization ever invented, and it arrives just as the United States, through the GENIUS Act, has signaled that it welcomes wider use of regulated dollar tokens abroad.
The central banker's dilemma
Monetary policy works through a country's own currency. When a central bank raises rates, it expects savers and borrowers in local money to respond. If a large share of savings and commerce migrates to dollar tokens, the lever loses some of its grip. Seigniorage, the income a state earns from issuing money, shrinks. Banks lose deposits that would otherwise fund domestic lending. And in a crisis, the rush into stablecoins can accelerate the very currency depreciation that authorities are trying to stop.
International institutions have been blunt about this. The IMF has warned for several years that widespread crypto and stablecoin adoption could undermine monetary sovereignty and capital flow management in vulnerable economies. The Bank for International Settlements, in its 2025 annual report, argued that stablecoins fall short on the basic tests of sound money, including the idea that every unit of money should trade at par with every other.
A stablecoin is the easiest form of dollarization ever built. That is its appeal and its threat, depending on who is holding the phone.
Four policy responses
Emerging-market governments have tried different approaches, none fully satisfactory.
| Approach | Example pattern | Trade-off |
|---|---|---|
| Prohibition | Banning banks from serving crypto firms | Activity moves to peer-to-peer markets |
| Licensing and taxation | Registering exchanges, taxing gains | Legitimizes use; limited effect on outflows |
| Local-currency tokens | Encouraging stablecoins pegged to the domestic currency | Little demand if the currency is the problem |
| Central bank digital currency | Issuing a CBDC to compete on convenience | Does not fix trust in the currency itself |
Nigeria offers a cautionary tale for prohibition. Restrictions on banks dealing with crypto firms earlier in the decade did not stop usage; they pushed it into peer-to-peer channels that were harder to monitor, and the country later moved toward licensing instead. Its central bank digital currency, the eNaira, saw limited uptake despite official promotion. Argentina has experienced the opposite: a relatively permissive environment in which stablecoins became part of everyday financial life for many people during years of high inflation.
The deeper issue is trust, not technology
What the experience of the past few years suggests is that stablecoins are a symptom more than a cause. People reach for dollar tokens because they do not trust the local currency, the banking system or the rules around moving money. Technology lowers the cost of acting on that distrust, but it does not create it. Central banks that regain credibility through stable prices and predictable policy tend to see less pressure; those that do not find that bans only change the route.
That said, there are practical tools. Coordinating with exchanges and wallet providers on reporting, applying capital flow measures to on- and off-ramps, and working through international standard setters such as the Financial Stability Board can reduce the most disruptive flows. Some economists also argue that host countries should have a say in how foreign stablecoin issuers operate within their borders, much as bank regulators do with foreign bank branches.
There is also a fairness argument that deserves more attention than it gets. The benefits of a dollar stablecoin, from reserve income to network effects, accrue mainly to the issuer and, indirectly, to the United States. The costs, in weaker monetary transmission and lost seigniorage, fall on the host country. In the era of physical dollarization, that asymmetry was accepted as a fact of life. In a world where a few firms can distribute dollar claims to hundreds of millions of phones, it becomes a legitimate subject for international negotiation. Forums such as the G20 and the IMF are natural places for that debate, even if the United States has little incentive to concede much.
What comes next
As US implementation of its stablecoin law advances and more regulated dollar tokens reach the market, the pull on emerging-market savings is likely to grow rather than shrink. The question for central banks is whether they can make their own money attractive enough, and their rules clear enough, that stablecoins become a complement rather than a substitute. That is a macroeconomic challenge first and a technological one second. This analysis is not investment advice; it is an argument that the most important variable in digital dollarization is still old-fashioned monetary credibility.