Aug 14, 2025, 6:37 AM
by
Nathan Reeves
5 min read
A Field Guide to Political Crypto: Tokens, Stablecoins and the Brands Behind Them
Aug 14, 2025, 6:37 AM · by Nathan Reeves
Political crypto is no longer one thing. Meme coins, governance tokens and dollar stablecoins carry very different risks, even when the same names sit on top.
Eighteen months ago, "political crypto" meant a handful of joke tokens named after candidates, traded by a few thousand enthusiasts who treated the 2024 race as a betting market with better memes. Today the phrase covers a sitting president's meme coin, a family-linked decentralized finance venture with its own dollar stablecoin, and a federal statute that sets the rules for that stablecoin's reserves. The category has grown up faster than most investors' mental models of it, and lumping everything together is now the fastest way to misjudge risk.
The useful move is to separate products by what they actually are, not by whose name is on them. A meme coin, a governance token and a payment stablecoin can share branding and still behave like three entirely different assets.
From PolitiFi jokes to presidential products
The first wave, loosely labeled PolitiFi by traders during the 2024 campaign, consisted of unofficial tokens riffing on candidates. They had no link to the people they parodied, no cash flows and no purpose beyond speculation on news and sentiment. Their prices tracked polls, debate clips and viral moments, and most lost the bulk of their value once the election passed.
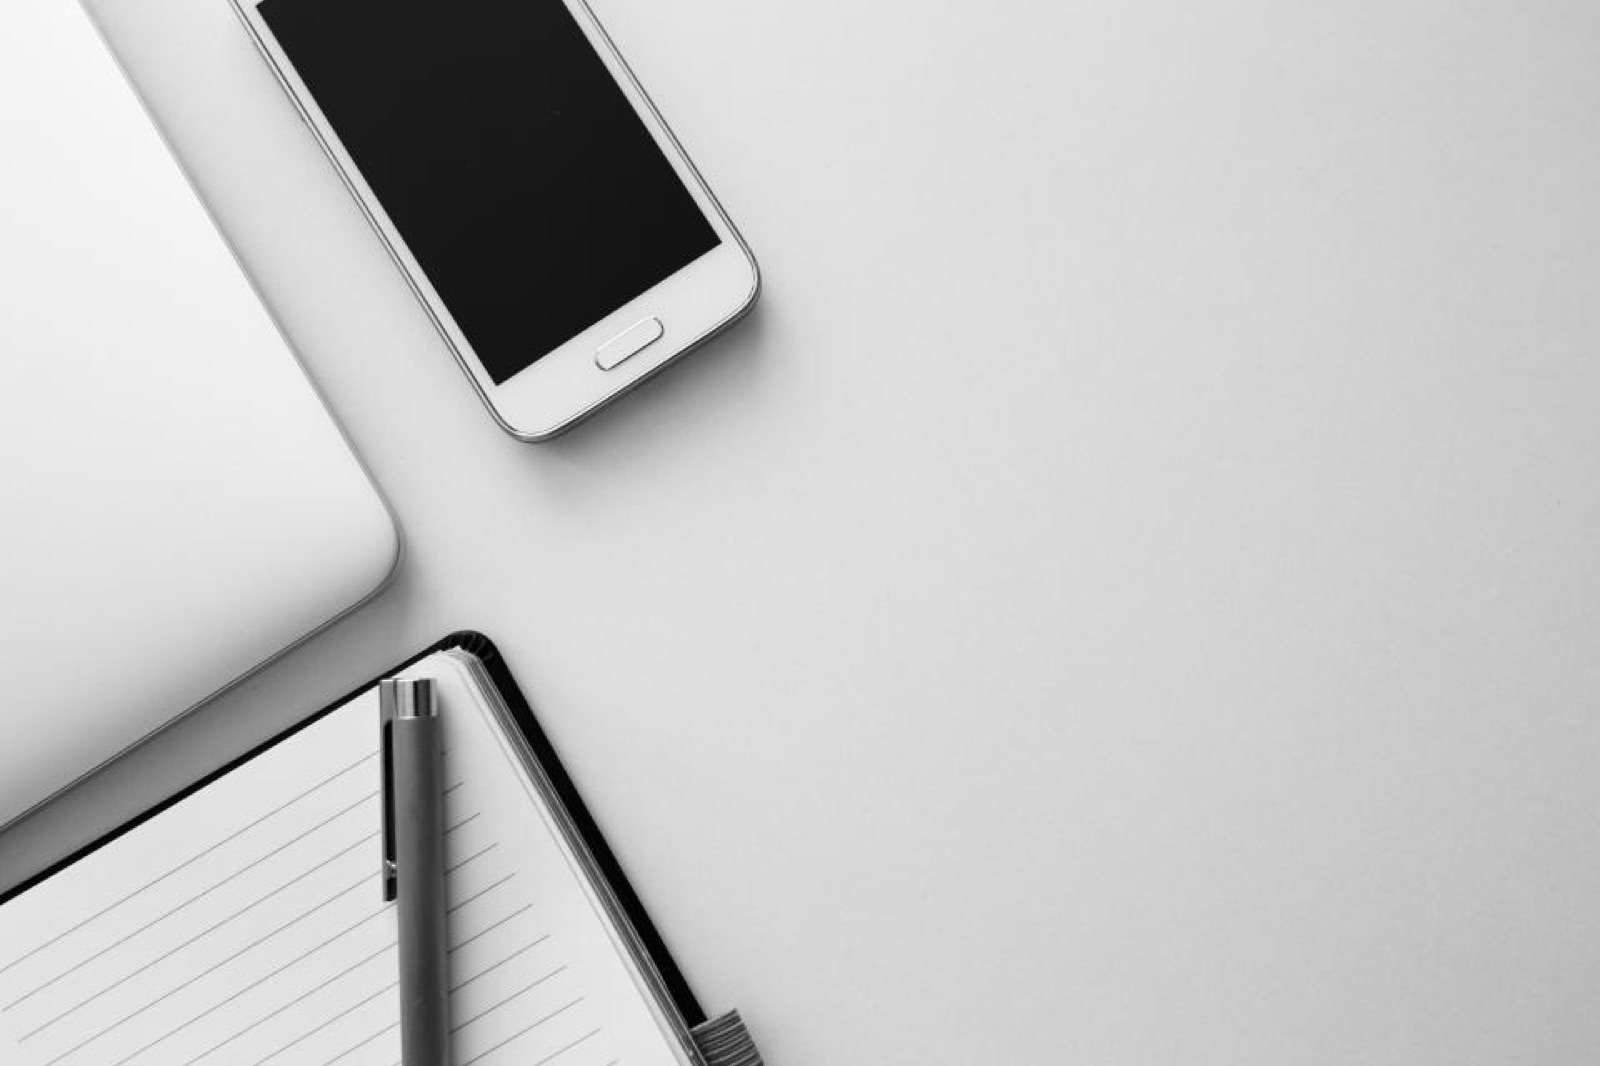
The second wave began in January 2025, days before the inauguration, when an official $TRUMP meme coin launched on the Solana blockchain, followed shortly by a $MELANIA token. The key difference was provenance. These were not parodies; they were licensed products associated with the Trump organization, with a large majority of supply held by affiliated entities and released on a vesting schedule. Prices spiked within hours and then fell sharply over the following weeks, a pattern familiar to anyone who has watched meme coin launches before.
The third wave is structurally different again. World Liberty Financial, a decentralized finance project launched in 2024 with members of the Trump family in promotional and ownership roles, introduced a dollar stablecoin called USD1 in the spring. Stablecoins are not bets on attention. They are supposed to be boring, fully reserved and redeemable at one dollar. USD1 was reported to have been used in a roughly $2 billion investment by an Abu Dhabi fund into the exchange Binance, which put a politically connected payment token inside a large cross-border deal almost immediately.
Three products, three risk profiles
Once you strip away the branding, the risks cluster very differently.
| Product type | What holders own | Main risk | Where politics enters |
|---|---|---|---|
| Meme coin | A token with no claim on anything | Price collapse, insider supply unlocks | Value depends on attention to a political figure |
| Governance token | Voting rights in a protocol, often with transfer limits | Illiquidity, concentrated control | Founders' public roles shape perception and regulation |
| Stablecoin | A claim on reserve assets, redeemable at par | Reserve quality, redemption stress | Issuer's links to officials who shape the rules |
For a meme coin, the political name is the product. There is nothing underneath it, so the price is a pure function of how much attention the figure commands and how much supply insiders release. For a stablecoin, the political name should be almost irrelevant to holders if reserves are sound, but it becomes highly relevant to regulators, counterparties and critics worried about influence.
What the GENIUS Act changes, and what it does not
The GENIUS Act, signed in July, created the first federal framework for payment stablecoins in the United States. It requires issuers to back tokens one-for-one with high-quality liquid assets such as cash and short-term Treasuries, publish regular reserve disclosures and submit to federal or qualifying state supervision. For a product like USD1, that means a clearer set of rules on reserves and redemptions than existed before.
What the law does not do is settle the political question. During the debate, several senators pushed amendments that would have barred senior officials and their families from issuing or profiting from stablecoins. Those provisions did not make it into the final text in the form critics wanted. The law therefore governs how a stablecoin must be run, not who is allowed to own the issuer.
A statute can tell an issuer what to hold in reserve. It cannot make a token's owners politically neutral.
Meme coins sit outside this framework entirely. Earlier this year, SEC staff indicated that typical meme coins are generally not securities, which removes one layer of oversight but also removes the disclosure obligations that securities law would impose.
The risks that matter for ordinary holders
For anyone looking at politically branded tokens, a few questions do most of the work:
- Who holds the supply, and when does it unlock? Concentrated insider allocations with scheduled releases are the single biggest source of downside in meme coins.
- What is the claim? A stablecoin holder has a claim on reserves; a meme coin holder has a claim on nothing.
- What happens if the political figure loses relevance or office? Attention decays, and so does any price built on it.
- Which regulator is responsible? Products that fall between frameworks give holders the fewest protections.
There is also a reputational dimension that rarely shows up in price charts. Counterparties such as banks, payment firms and exchanges increasingly weigh political exposure when they decide what to list or support. A token that looks attractive during one administration can become awkward to hold in a compliance department's eyes under the next.
Where this leaves the category
Political crypto has split into a speculative end and an infrastructural end. The speculative end looks much like it did in 2024, just with bigger names and faster cycles. The infrastructural end, led by stablecoins, now operates inside federal law and will be judged on reserves and redemptions like any other issuer.
The open question is whether the second can escape the reputation of the first. For now, the safest assumption is that the political name on a token tells you more about its headline risk than about its fundamentals. None of this is investment advice; it is a map, and the territory is still moving.